When the logical buyer
is another company.
We facilitate M&A transactions for businesses where the buyer is a company or an investment group rather than an individual operator, whether you are seeking a full acquisition, a partial recapitalization, or a strategic partnership.
If your business generates substantial earnings, operates in a consolidating industry, or holds assets that create strategic value for an acquirer, M&A is the framework for an exit or for growth capital.
Transaction process.
Mergers and acquisitions operate at a different level than a standard business sale. The buyers are sophisticated: private equity groups, strategic corporate acquirers, investment firms, and high net worth individuals seeking larger transactions or a specific market position. The transactions are more complex, involving extensive due diligence, sophisticated deal structures, and a heavier legal framework.
That requires different expertise than standard brokerage. The planning timeline runs in months rather than weeks. Confidentiality protocols are institutional grade. Tax structuring becomes critical: entity type, asset versus stock sale, earnout provisions, and timing each carry sizable tax implications that land directly on your net proceeds.
When M&A makes sense.
M&A becomes relevant when a business is large enough, distinct enough, or positioned such that the highest-value buyer is another company or an institutional investor rather than an individual operator. In practice that usually means a business generating over $1M in seller's discretionary earnings.
The buyer universe for an M&A transaction is fundamentally different from the one for a main-street sale, which means different marketing, different deal structures, and different execution timelines.
Private equity groups seeking platform acquisitions and add-on bolt-ons.
Corporate buyers pursuing geographic expansion or a capability they would rather buy than build.
Family offices making direct investments.
Search funds run by MBA-trained acquisition entrepreneurs.
Deal counsel from
inside the firm.
This is the part most brokerages hand to a referral you meet for the first time at closing. Devon advises on structure and documentation whoever is running the transaction, so the legal read comes from someone already familiar with the deal rather than someone reading it cold.
Deal documentation at this level expands to include non-compete agreements, employment contracts, consulting arrangements, management agreements, escrow provisions, earnout formulas, indemnification caps, and representations and warranties. Both sides need experienced M&A counsel to negotiate terms that protect their interests while still letting the deal close.
Many M&A transactions are partial sales, where the owner retains equity and keeps running the business toward a planned later exit. Those require more sophisticated agreements than a full sale, not fewer, because both parties stay invested in future performance and in the working relationship that produces it.
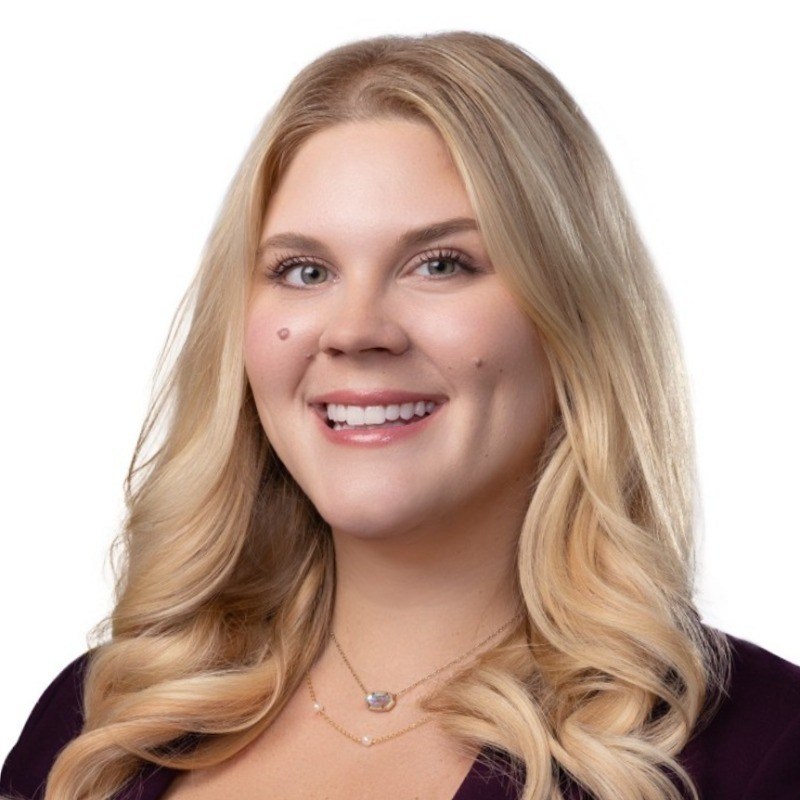
Attorney at Maynard Nexsen with a background in construction and commercial litigation, covering 75+ legal matters totaling over $40M in settlements and contracts. Admitted to the bar in Georgia and Tennessee, and licensed in real estate across Georgia, Tennessee, and South Carolina.
If your company qualifies,
the conversation is free.
If you are considering exit options for a substantial business, exploring a recapitalization to take chips off the table while keeping operational control, or evaluating a strategic partnership that accelerates growth, M&A is the right framework.
The complexity is real and the costs are higher. Structured properly, with experienced advisors on both sides, the outcome is materially better than treating a sophisticated transaction like a simple business sale.